Rose Street Advisors Rose Street Advisors
Firm
About UsOur TeamM Financial GroupEducation LibraryCommunity SupportTestimonials
Benefits
Employee Benefit ServicesBenefits FAQBenefits University Blog
HR Consulting
HR Consulting ServicesHR BlogRose Street Recruits
Life Insurance
Life Insurance ServicesLife Happens BlogLife Insurance Vlog
Employer Retirement Plans
Retirement ServicesFiduciary Fitness ProgramGuide to Retirement BlogRetirement Plans FAQ
Wealth Management
Wealth Management ServicesInvestED BlogWealth Management FAQs
Get In Touch

Turning on Social Security can feel like a simple decision. You reach 62, you're eligible, so why not start collecting?  For some retirees, claiming early may make sense. But starting Social Security before you fully understand the consequences can create some unwelcome surprises.

Here are 4 reasons to think twice before turning it on.

  1. 1. You Could Lock In a Smaller Benefit

You can start Social Security as early as age 62, but claiming before Full Retirement Age permanently reduces your monthly benefit.

And there's another side to the equation: waiting can significantly increase your benefit.

Delaying Social Security beyond 62e earns 7-8% in delayed retirement credits for each full year you wait, up to age 70. That means someone with a Full Retirement Age of 67 could potentially receive 24% more by waiting until 70, before cost-of-living adjustments.

The decision isn't simply whether you want the money now. It's whether you want a smaller benefit for life or a larger guaranteed benefit later.

  1. 2. Going Back to Work Could Reduce Your Benefits

What if you start Social Security and then decide you're not ready to stop working?

If you're under Full Retirement Age and earn more than the annual earnings limit, some of your benefits can be withheld. In 2026, that limit is $24,480 for someone under Full Retirement Age for the entire year.

You may be able to recover some of the withheld value later, but the immediate impact on your income can be an unwelcome surprise.

  1. 3. You Could Trigger Higher Medicare Premiums

This is one many retirees don't see coming.

Higher income can trigger IRMAA, which means higher Medicare Part B and Part D premiums.

And here's the kicker: Medicare generally looks at your income from two years earlier.

So a decision you make today could mean higher Medicare premiums two years from now.

  1. 4. It Can Affect Your Spouse

Social Security isn't just an individual decision when you're married.

Your claiming strategy can affect your spouse's benefits, particularly when it comes to survivor benefits.

The higher-earning spouse's decision can be especially important because the surviving spouse may ultimately depend on that benefit.

Don't just ask, "When should I claim?" Ask, "When should we claim?"

The Bigger Question

The question isn't simply:

"Can I start Social Security?"

It's:

"What happens if I start Social Security now?"

What happens to your taxes? What happens to Medicare? What happens if you go back to work? What happens to your spouse? What happens to your future income?

At Rose Street Advisors, we use sophisticated planning technology to help retirees model different Social Security strategies and see how each decision could affect their overall retirement plan.

Before you turn on Social Security, make sure you understand what else you're turning on.

Contact Rose Street Advisors to see how Social Security fits into your retirement plan.

Jeremy Heavey

AIF ® , NSSA ® | FINANCIAL ADVISOR

Securities and Investment Advisory Services offered through M Holdings Securities, Inc., a Registered Broker/Dealer and Investment Advisor, Member FINRA/SIPC. Rose Street Advisors, LLC is independently owned and operated. File #5944657

Interested in more?

Let's Talk Proactive HR

At Rose Street Advisors, we help retirees evaluate and execute Roth conversions every year. For many clients, a Roth conversion can be an important part of a thoughtful retirement and tax strategy.  But we've also learned something important:

Just because you can do a Roth conversion doesn't mean you should.

The right question isn't how much you can convert. It's whether converting makes sense for your specific situation.  Here are five situations where retirees should think twice.

  1. 1. You Don't Have Heirs Who Will Benefit

One of the biggest potential benefits of a Roth is leaving tax-free assets to your heirs.

But what if you don't plan to leave significant assets to children or other beneficiaries?  If your goal is to spend your retirement assets during your lifetime, paying taxes today to create a tax-free inheritance may provide little benefit.

There may still be reasons to convert, such as reducing future RMDs or managing future taxable income. But the conversion should have a clear purpose.

If nobody is going to benefit from the Roth later, ask why you're paying the tax today.

  1. 2. You're Planning to Give the Money to Charity

Retirement accounts can be valuable charitable assets.

If you plan to leave a significant portion of your IRA to charity, converting those dollars to a Roth first may mean paying taxes on money that could potentially pass directly to a qualified charity without creating the same income-tax burden.  The better question may not be, "How much should I convert?"

It may be, "Which assets should go to charity and which should go to my family?"

Sometimes the best Roth conversion is the one you don't make.

  1. 3. You Don't Have Cash to Pay the Taxes

A Roth conversion creates taxable income.  If you convert $200,000 and owe $50,000 in federal and state taxes, where will that $50,000 come from?  Ideally, you pay the tax with money outside the IRA. Otherwise, you may have to use part of the retirement account to pay the tax, reducing the amount that actually makes it into the Roth.

Before converting, make sure you have a plan for the tax bill.

  1. 4. The Conversion Will Increase Your Medicare Premiums

For retirees on Medicare, don't forget about IRMAA, the Income-Related Monthly Adjustment Amount. A Roth conversion can increase your income enough to trigger higher Medicare Part B and Part D premiums.  And there's a two-year lookback.

For example, a conversion in 2026 can affect your Medicare premiums in 2028.  But here's the important point: paying additional IRMAA isn't necessarily a mistake.

If a larger Roth conversion meaningfully reduces future RMDs, creates more tax-free assets for heirs, or provides other long-term benefits, paying higher Medicare premiums for a year or two may be a reasonable tradeoff.  The mistake is ignoring IRMAA when doing the math.

  1. 5. You May Be in a Lower Tax Bracket Later

A Roth conversion means paying taxes today in exchange for potentially avoiding taxes later.  So what will your tax bracket look like in the future?  If your income is unusually high today but is expected to fall in future years, a large conversion may not make sense right now.

This is why Roth conversion planning should often be viewed as a multiyear strategy, not a one-time decision.  You may convert some this year, more next year, and less the year after.

The Bigger Question

The question isn't: "Should I do a Roth conversion?" It's:

"Does paying the tax today create enough value to justify the cost?"

That requires looking at taxes, RMDs, Medicare premiums, charitable intentions, estate plans, and how you actually intend to use your money.

At Rose Street Advisors, we use state-of-the-art planning technology to model these decisions and help clients see the potential tax impact of different Roth conversion strategies before making a decision.

Sometimes the answer is to convert.  Sometimes the answer is to wait.  And sometimes the answer is don't convert at all.

Don't convert just because you can. Convert because it serves a purpose.

Good retirement planning isn't about finding the latest strategy and checking a box.

It's about making sure every financial decision has a purpose.

If you're wondering whether a Roth conversion makes sense for your retirement plan, contact Rose Street Advisors.We'd be happy to help you evaluate the numbers, the tradeoffs, and the potential long-term impact of a conversion.

Contact us to see whether a Roth conversion is right for you.

Jeremy Heavey

AIF ® , NSSA ® | FINANCIAL ADVISOR

Securities and Investment Advisory Services offered through M Holdings Securities, Inc., a Registered Broker/Dealer and Investment Advisor, Member FINRA/SIPC. Rose Street Advisors, LLC is independently owned and operated. File #5943979

Interested in more?

Let's Talk Proactive HR

If your parent is still alive but the end may be near, we recommend reading our article "What To Do When the End Is Near." That guide walks through important conversations, documents, and financial steps that can make everything that follows much smoother. Preparing ahead of time can reduce stress, prevent delays, and help families move forward with greater clarity.

When your last parent passes away, you’re not just grieving. You’re stepping into a new role. You’re now the next generation. The one responsible for decisions, communication, and organization.

That can feel overwhelming. This guide is designed so someone could sit at a kitchen table and simply start working through it.

Before the checklist, one of the most helpful things to understand is timeline. Many families feel pressure to wrap things up quickly. In reality, settling an estate takes time, and that is completely normal.

A Realistic Timeline (So You Can Set Expectations)

First 1–2 weeks Order death certificates Secure home and assets Locate documents Notify financial advisor Begin gathering account information

Weeks 3–4 Contact attorney if probate may be needed Determine beneficiaries Create initial asset list Confirm executor or trustee Continue notifications

2–6 months Open estate if needed Pay bills and expenses Collect insurance proceeds Transfer accounts Prepare home for sale if applicable Complete required distributions

6–12 months (sometimes longer) File final tax return Resolve outstanding issues Distribute remaining assets Close estate

Important note to communicate to heirs

It is wise not to distribute money immediately. Taxes, expenses, and unknowns can arise. Moving slowly protects everyone and avoids asking for money back later.

You can say

"We are working through everything carefully. Most estates take several months to settle. We want to make sure taxes, expenses, and paperwork are handled correctly before distributions."

  1. 1. Slow Down Before Making Major Decisions

This is not the time to sell the house, move money, or divide assets. Grief impacts judgment. Very few financial decisions are urgent, but many mistakes happen when people move too quickly.

Pause. Gather information. Communicate. Then decide.

According to Cerulli Associates, $84 trillion is expected to transfer from older generations to heirs over the next two decades. These decisions are often large. Taking time matters.

  1. 2. Order Death Certificates

You will likely need death certificates, but fewer organizations require original copies today than in the past.

Ordering 5 to 8 copies is typically sufficient. In many cases, scanned copies are accepted. The most common situations requiring original death certificates include transferring real estate through the Register of Deeds and the occasional financial institution.

Where to order
• Funeral home (easiest)
• County clerk
• State vital records office


Immediately after receiving them Create a high-quality digital scan. Many organizations accept digital copies.

Checklist
☐ Order multiple copies (5–8 typically sufficient)
☐ Create digital scan
☐ Store originals safely


  1. 3. Secure the Home and Immediate Assets

This protects against theft, damage, and insurance issues.

Checklist
☐ Lock home
☐ Confirm homeowners insurance active
☐ Forward mail
☐ Maintain utilities
☐ Care for pets or dependents
☐ Remove obvious valuables if needed


  1. 4. Notify Key Organizations

This stops payments, prevents fraud, and starts transitions.

In many cases, the funeral home notifies Social Security, which then flows through to Medicare and Medicaid. Because of this, families often do not need to contact these agencies directly. However, it is still wise to confirm benefits have stopped appropriately.

What to say when calling

"I'm calling to report the death of [Name]. They passed away on [date]. I'm [relationship]. What do you need from me and what are the next steps?"

They may ask for
• Name
• Date of death
• Social Security number
• Death certificate
• Your contact information


Notify these first

Financial
☐ Banks
☐ Investment firms
☐ Retirement accounts
☐ Pension providers


Insurance
☐ Life insurance
☐ Homeowners insurance
☐ Auto insurance


Professional contacts
☐ Financial advisor
☐ CPA
☐ Attorney


Employer if applicable
Ask about
• Final paycheck
• Pension
• 401(k)v • Life insurance


How to Notify Credit Bureaus (Identity Theft Protection)

Experian 888-397-3742

Equifax 888-548-7878

TransUnion 800-680-7289

What they need
• Name
• Social Security number
• Date of death
• Death certificate


Ask them to
• Flag file as deceased
• Send credit report
• Block new credit


Important tip Ask each organization what they need. Some require originals, others accept digital copies.

  1. 5. Contact the Financial Advisor

This is one of the most important early calls. You do not need multiple calls. Ask them to gather everything.

Tell them

"My parent passed away. Can you help me gather everything and outline next steps?"

  • Ask them to provide List of all accounts
    • Beneficiaries on each account
    • Date-of-death values
    • Step-up in cost basis values
    • Required distributions
    • Life Insurance Policies
  • What paperwork is needed Which assets avoid probate
    • Estimated timeline

Checklist
☐ Notify advisor of death
☐ Request full asset list
☐ Request beneficiaries
☐ Request date-of-death values
☐ Ask about required distribution
☐ Ask what paperwork is needed


  1. 6. Gather Important Documents

Checklist
☐ Will or trust
☐ Account statements
☐ Life insurance policies
☐ Property deeds
☐ Tax returns
☐ Mortgage information


Where to look:
File cabinets
Safe deposit box
Attorney
Financial advisor
CPA
Mail
Email


Additional place many families overlook For older estates, the original will may be held at the probate court in the county where your parent lived. Decades ago, safekeeping wills at the court was common practice. While this is no longer standard, it is still worth checking, especially if documents cannot be located.

Executor or Trustee This is the person responsible for handling everything. They gather assets, pay bills, and distribute money according to the will or trust.

  1. 7. Determine if Probate or an Estate is Needed

What is probate Probate is the legal process that gives someone authority to act on behalf of the deceased. The court formally appoints the executor.

You may need probate if Assets in one name only No beneficiary listed No trust exists

You may NOT need probate if Assets in trust Beneficiary designations Joint ownership

Timing matters It often takes three to four weeks or longer for the court to open probate and issue Letters of Authority. Delays in starting this process can push back creditor notice periods and slow the overall timeline. If probate is likely, contacting an attorney within the first three to four weeks is typically helpful.

Opening an estate means Creating a legal entity called "The Estate of [Name]" so money can be collected and bills paid.

This often includes Court appointment if needed Opening estate checking account Depositing incoming funds Paying expenses

Checklist
☐ Determine if probate required
☐ Contact attorney within 3–4 weeks if needed
☐ File will with court if needed
☐ Receive executor authority
☐ Open estate checking account
☐ Pay bills from estate account
☐ Track expenses


  1. 8. Create a List of Assets and Debts

Checklist
☐ Bank accounts
☐ Investment accounts
☐ Retirement accounts
☐ Life insurance
☐ Real estate
☐ Vehicles
☐ Personal property
☐ Debts
☐ Mortgage
☐ Credit cards
☐ Medical bills


  1. 9. Understand Step-Up in Cost Basis and Handle Tax Valuations

One of the most important financial opportunities after a parent passes away is something called a step-up in cost basis. This can significantly reduce taxes for heirs.

What is step-up in cost basis When someone inherits investments or property, the value resets to the date-of-death value, not what the parent originally paid.

Capital gains tax is based on the difference between sale price and cost basis. The step-up eliminates taxes on gains that happened during your parent’s lifetime.

Example with investments

Your parent bought a stock for $20,000 At death, it is worth $100,000 You sell for $102,000

Without step-up Taxable gain = $82,000

With step-up Taxable gain = $2,000

Example with real estate

Parent bought home for $150,000 Value at death $400,000 You sell for $410,000

Without step-up Gain = $260,000

With step-up Gain = $10,000

Who provides values

Investments Your financial advisor typically provides
• Date of death values
• Cost basis reset
• Documentation


Ask them on the first call.

Real estate You can determine value using
• Real estate agent comparative market analysis
• Appraisal
• County tax value
• Online estimates as temporary reference


Checklist
☐ Request date-of-death values from advisor
☐ Confirm step-up applied
☐ Obtain real estate value
☐ Document values
☐ Avoid selling before confirmed
☐ Coordinate with tax preparer
☐ File final income tax return


  1. 10. Don’t Distribute Money Too Quickly

There may still be Taxes Bills Legal costs Unknown expenses

Checklist
☐ Identify expenses
☐ Set aside reserves
☐ Communicate timeline to heirs
☐ Distribute when clear


Where to Start First

☐ Order death certificates
☐ Secure home
☐ Notify financial advisor
☐ Contact attorney (if probate likely)
☐ Notify banks and institutions
☐ Gather documents
☐ Determine executor
☐ Create asset list


You do not need to do everything today. You just need to begin.

About Rose Street Advisors Wealth Management

At Rose Street Advisors Wealth Management, we work closely with individuals and families navigating life’s biggest financial transitions. Losing a parent and settling an estate is not just a financial process. It is emotional, relational, and often filled with decisions most people have never had to make before.

Our role is to bring clarity and calm to complex situations. We help families organize accounts, understand beneficiaries, coordinate with attorneys and tax professionals, determine step-up in cost basis values, and create a thoughtful timeline for distributions. Just as importantly, we help families avoid rushed decisions that can create unnecessary taxes or tension.

We often serve as a central point of coordination, helping ensure nothing is missed while allowing families to move at a thoughtful pace.

If you are walking through this process, you do not have to do it alone. We would be honored to help you think through next steps, answer questions, or simply provide guidance during a difficult season.

Please reach out to our team. We would be glad to help.

Jeremy Heavey

AIF ® , NSSA ® | FINANCIAL ADVISOR

Securities and Investment Advisory Services offered through M Holdings Securities, Inc., a Registered Broker/Dealer and Investment Advisor, Member FINRA/SIPC. Rose Street Advisors, LLC is independently owned and operated. File #5350468

Interested in more?

Let's Talk Proactive HR

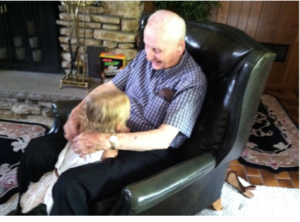
The pic is a little blury, but one that we will never get rid of.  We knew the end with my Grandpa was near, but didn’t know how near.  This was the last picture we have of my Grandpa and my oldest.  The look on his face tells the story.  He loved this moment!  He was an incredible man of faith, lover of kids and quiet powerhouse of a leader.  He led by serving people.  What a joy to have my daughter get a chance to spend a couple years with him before he passed away.  He and my Grandma were married for 66 years and led a life serving others.  They died within 8 months of each other.  What a legacy they built and left.

When a parent’s health is declining and the end may be near, families often feel two things at the same time. Emotionally, you want to be present. Practically, you know there are things that should be handled. This guide is meant to help you do both. You do not need to do everything at once.  You just need to start.

1. Have the Most Important Conversation

If your parent is able, this is the most valuable step.

Discuss
• Who makes medical decisions
• Who handles finances
• Care preferences (hospice, hospital, life support)
• Funeral wishes
• Where documents are located
• How assets should be handled
• Who communicates with family

Checklist
☐ Identify medical decision maker
☐ Identify financial decision maker
☐ Discuss care preferences
☐ Discuss funeral wishes
☐ Ask where documents are located

  1. Confirm Legal Documents

These allow you to act before death, not just after.

Important documents
• Will or trust
• Financial power of attorney
• Healthcare power of attorney
• Living will / advance directive
• HIPAA authorization
• Beneficiary designations

Double check life insurance beneficiaries. These override a will and are often outdated.

Checklist
☐ Locate will or trust
☐ Confirm financial POA
☐ Confirm healthcare POA
☐ Confirm advance directive
☐ Review retirement beneficiaries
☐ Review life insurance beneficiaries

  1. Identify Decision Makers

You should know:
• Medical decision maker
• Financial decision maker
• Executor
• Family communicator

Checklist
☐ Identify roles
☐ Share roles with family

  1. Gather Financial Information

You are simply identifying what exists.

Include
• Bank accounts
• Investment accounts
• Retirement accounts
• Life insurance
• Annuities
• Real estate
• Debts

Checklist
☐ List accounts
☐ List insurance
☐ List debts
☐ Gather statements

  1. Contact the Financial Advisor

They can help organize everything and prepare for what comes next.

They help with
• Account list
• Beneficiaries
• Life insurance review
• What avoids probate
• Liquidity needs
• Next steps

Checklist
☐ Notify advisor
☐ Request account list
☐ Confirm beneficiaries
☐ Double check life insurance beneficiaries
☐ Ask what to prepare now

  1. Understand What Transfers Automatically

Some assets transfer immediately
• Life insurance with beneficiary
• Retirement accounts with beneficiary
• Joint accounts
• Trust assets

Others may require probate
• Assets in one name
• No beneficiary
• No trust

Checklist
☐ Identify beneficiary accounts
☐ Identify probate assets

  1. Discuss the Home

This is often the largest decision.

Discuss
• Keep or sell
• Who maintains it
• Where documents are
• Mortgage and insurance

Checklist
☐ Discuss home plan
☐ Locate deed
☐ Confirm insurance

  1. Discuss Funeral Preferences

Consider
• Burial or cremation
• Funeral home
• Service preferences
• Cemetery
• Obituary

Checklist
☐ Burial vs cremation
☐ Funeral home
☐ Service preferences

  1. Determine How Expenses Will Be Paid

This prevents stress immediately after death.

Identify
• Life insurance
• Prepaid funeral plans
• Liquid accounts
• Who pays upfront expenses

Checklist
☐ Identify life insurance
☐ Confirm beneficiaries
☐ Identify liquid fund
☐ Determine who pays upfront

  1. Gather Digital Access

Often overlooked but extremely helpful.

Include
• Phone passcode
• Email access
• Financial logins
• Subscriptions
• Social media

Checklist
☐ Document phone access
☐ Document email access
☐ Document financial logins

  1. Create a Simple Information Sheet

Include
• Full name
• Social Security number
• Date of birth
• Advisor contact
• Attorney contact
• Account list
• Document locations

Checklist
☐ Create information sheet
☐ Share with trusted person

  1. Share Document Locations

Make sure the right people know where everything is.

Checklist
☐ Share document locations
☐ Provide copies to decision makers
☐ Confirm safe deposit box access

Where to Start First

☐ Have the conversation
☐ Identify decision makers
☐ Locate will and documents
☐ Double check life insurance beneficiaries
☐ Contact financial advisor
☐ List accounts
☐ Discuss funeral wishes
☐ Determine expense funding

You do not need to do everything today. You just need to begin.

About Rose Street Advisors Wealth Management

At Rose Street Advisors Wealth Management, we often walk alongside families during life’s most difficult transitions. When a parent’s health is declining, decisions become both emotional and practical. Many families are unsure what should be handled now versus later.

Our role is to bring clarity and calm during an uncertain time. We help families organize accounts, review beneficiaries, coordinate with attorneys, identify what will transfer smoothly, and prepare for the decisions that follow. Just as importantly, we help families avoid rushed decisions and focus on what matters most.

Planning ahead does not make this season easier emotionally, but it can remove uncertainty and reduce stress for everyone involved.

If your family is navigating this stage, we would be honored to help you think through next steps, answer questions, or simply provide guidance.

Jeremy Heavey

AIF ® , NSSA ® | FINANCIAL ADVISOR

Securities and Investment Advisory Services offered through M Holdings Securities, Inc., a Registered Broker/Dealer and Investment Advisor, Member FINRA/SIPC. Rose Street Advisors, LLC is independently owned and operated. File #5350478

Interested in more?

Let's Talk Proactive HR

Have you ever noticed how something as simple as toothpaste can tell you a lot about your life?

This morning, I walked into the bathroom and, to my surprise, my toothpaste was exactly where it belonged. Right there. In the drawer. Waiting for me. If you have teenagers in your house, you know that’s not always how it works.

In our home, Kim and I joke that some of our things behave a lot like our old outdoor cat, Oliver. He came and went as he pleased. Some days he’d stick around. Other days, he’d disappear without a trace. That’s pretty much how our stuff operates too. Toothpaste, conditioner, chargers, hoodies… here today, gone tomorrow. You get the idea.

Kim said something this morning that stuck with me. “As frustrating as it is, when the kids are gone, we might actually miss this.”

I told her when that day comes, I’ll gladly take her things and hide them around the house just to keep her on her toes. #winning

But there’s something deeper in that.

We don’t always realize what we’ll miss until it’s gone. And that shows up clearly in retirement.

Most people spend decades focused on the numbers. How much have I saved? Will it be enough? When can I stop working? Important questions, and we help answer them every day. But there’s another question that matters just as much.

What will your days actually feel like when the house is quieter, the calendar is clearer, and everything is exactly where you left it?

I’ve seen it often. People are financially ready, but not fully prepared for the shift. They expected freedom. They got it. What they didn’t expect was the loss of rhythm, noise, responsibility, and even the small frustrations that once filled their days.

Retirement isn’t just a financial transition. It’s a life transition.

The people who navigate it best have taken time to picture it ahead of time. Not just the big trips, but the ordinary Tuesdays.

At Rose Street Advisors, that’s a big part of what we do. Yes, we build income strategies and think through taxes and risk. But we also help clients get clear on the life behind the plan.

What does a great day look like? Who are you spending time with? What are you moving toward? Where does purpose come from when work no longer defines your schedule?

Because retirement without a clear picture can feel a lot like that outdoor cat. A little unpredictable. A little disorienting.

But when you define it, something changes.

You stop reacting… and start living with intention.

So here’s a simple place to start. Picture a random Tuesday in retirement. Not a vacation. Just a normal day.

Where are you?
What are you doing?
Who are you with?

Then ask yourself, if nothing changed between now and then, would that day feel fulfilling?

If not, that’s not a problem. It’s an opportunity. An opportunity to start shaping that future now.

Because the goal isn’t just to have enough.

It’s to build a life you’re excited to live.

And if more people approached retirement this way, I think we’d see fewer people drifting and more people fully stepping into what could be one of the most meaningful seasons of their lives.

And maybe, just maybe, keeping a little of that “outdoor cat” energy along the way.

Jeremy Heavey

AIF ® , NSSA ® | FINANCIAL ADVISOR

Securities and Investment Advisory Services offered through M Holdings Securities, Inc., a Registered Broker/Dealer and Investment Advisor, Member FINRA/SIPC. Rose Street Advisors, LLC is independently owned and operated. File #5321941

Interested in more?

Let's Talk Proactive HR

When meeting with our philanthropically minded clients, we often say, “give cash last.”  Donating cash is simple, but it’s not always the most tax efficient.  As we are nearing the end of the year, many clients plan to make charitable contributions, and it is our job to help make those contributions go as far as possible.  What does this mean for you?  If you have an IRA, investments like stocks or real estate that have appreciated over time, you might be better off donating those instead of cash. Why? Because by donating non-cash assets, you can often avoid capital gains taxes and/or income taxes. In other words, you’ll give more to charity without having to hand over extra cash to the government.  Here are the top 6 ways to get the biggest tax break for your donation:

1. Use Your IRA for Charitable Giving

Do you need to satisfy your Required Minimum Distributions (RMDs) from your IRA?   You can avoid the tax hit from those RMDs by donating directly from your IRA to charity through a Qualified Charitable Distribution (QCD).  Even if you are just 70 ½ and don’t have to take an RMD yet, you still maybe be eligible to give through a QCD.

How It Works:

• Contact your IRA provider and request a direct transfer to a qualified charity (or request a checkbook and write checks to charities yourself!

• The amount you give won’t be counted as taxable income, and it will satisfy your RMD.

Why It’s Smart: It’s a great way to reduce your taxable income while meeting your RMD requirement. It’s especially useful if you don’t need the income from your IRA for living expenses but still want to make a charitable impact.

2. Donate Appreciated Stocks, Bonds, or Mutual Funds

If you’ve got stocks, bonds, etfs or mutual funds in a taxable brokerage account that have increased in value since you bought them, this is one of the best ways to donate. Why?  When you donate these assets directly to a charity, you avoid paying capital gains taxes on the appreciation, and you get a tax deduction for the full market value of the securities.

How It Works:

• Look through your portfolio for any investments that have appreciated.

• Transfer the stocks, bonds, or funds directly to the charity (don’t sell them first).

• The charity then sells the investments tax-free and gets the proceeds to use for their cause.

Why It’s Smart: You avoid paying capital gains tax, so the value of your donation is higher. It’s a win-win—you give more, you get a tax break and the charity gets more.

3. Use a Donor-Advised Fund (DAF)

If you’re looking for flexibility, a donor-advised fund might be the perfect solution.

A DAF allows you to contribute cash or assets like stocks to an account, receive an immediate tax deduction, and then distribute the funds to charities over time. Think of it as your personal charitable giving account that you control. 

Donor Advised Funds are the fastest growing way to donate in the United States.  Because the standard deduction has been much higher in recent years, to get the biggest tax benefit, some investors are ‘bunching’ several years of giving into one tax year, getting the bigger tax benefit in that year, and then making distributions over the next several years. Think of giving more in a 2 year cycle that keeps repeating vs just giving directly from cash each year. 

For example, a donor might contribute $50k in one calendar year, receive the tax break for that year, and then make $25k worth of distributions in that year & another $25k worth of distributions in the next year, then load up the donor advised fund once again for another 2 year cycle.  This allows the donor to take the higher deduction in the year they are “bunching” their donations and the standard deduction in the “off years.”

How It Works:

• Set up a DAF through a sponsoring organization (most major financial institutions offer them).

• Donate assets like stocks or cash to the DAF.

• You get a tax deduction right away and then you can distribute grants to your favorite charities whenever you like.

Why It’s Smart: DAFs give you the freedom to plan your giving. You can invest the assets within the fund and let them grow, potentially increasing the amount you can eventually donate.

4. Give Tangible Personal Property (Art, Collectibles, etc.)

If you own valuable personal items like artwork, real estate, cars, or collectibles, these can also be donated to charity. Depending on the item and how it’s used by the charity, you may be able to deduct either the fair market value or the cost basis of the item.

How It Works:

• Donate items that are of significant value.

• If the charity can use the item (e.g., donating art to a museum), you may be able to deduct the fair market value.

• If the charity sells the item, the deduction might be based on the cost basis (what you originally paid for it).

Why It’s Smart: Donating tangible items can help you offload valuable but non-liquid assets while benefiting from a tax deduction. It’s a great option if you have personal property you no longer need or want.

5. Use Life Insurance

Using life insurance to donate is a great option if you want to make a significant future donation without needing to use other assets. You can either donate a policy you no longer need or make the charity the beneficiary of a current policy.

How It Works:

• Option 1: Transfer ownership of an existing policy to the charity. You may be able to deduct the policy’s cash value at the time of donation and premiums paid.

• Option 2: Name the charity as a beneficiary on a new or existing life insurance policy, ensuring a future gift.

Why It’s Smart: Donating life insurance allows you to make a larger impact over time, using minimal resources now. If you transfer ownership, you may also receive an immediate tax benefit for the policy’s value and any ongoing premiums paid.

6. Charitable Trusts

For those looking to make a significant impact while also planning for their estate, setting up a charitable trust can be a great way to give. There are different types of charitable trusts, such as Charitable Remainder Trusts (CRTs) and Charitable Lead Trusts (CLTs), which allow you to donate assets while retaining an income stream or passing assets to heirs.

How It Works:

• Set up a trust that holds appreciated assets like stocks or real estate.

• A Charitable Remainder Trust (CRT) provides you or your beneficiaries with income for a set period, and the remainder goes to the charity.

• A Charitable Lead Trust (CLT) directs income to the charity for a set time, after which the remainder goes to your heirs.

Why It’s Smart: Charitable trusts allow you to make a significant contribution while receiving tax benefits and potentially providing for your family. They are a great tool for those with complex financial or estate planning goals.

Final Thoughts

If you’re an investor, donating cash should be your last resort. By giving appreciated securities, real estate, personal property, a life insurance policy or leveraging tools like IRAs or charitable trusts, you can have more money be received by non-profits and realize significant tax advantages. The “give cash last” mentality allows you to do more with what you already have, making a bigger difference for the causes you care about while being smart with your financial resources.  Before you write that next check to charity, consider how some of your investments can reach even further….and get you a bigger tax break.  Want to explore your options? Let’s chat.

Jeremy Heavey

AIF ® , NSSA ® | FINANCIAL ADVISOR

This material and the opinions voiced are for general information only and are not intended to provide specific advice or recommendations for any individual or entity. To determine what is appropriate for you, please contact your Rose Street Financial Professional. Information obtained from third-party sources are believed to be reliable but not guaranteed.  The tax and legal references attached herein are provided with the understanding that neither M Financial Group, nor its Member Firms are engaged in rendering tax, legal, or actuarial services. If tax, legal, or actuarial advice is required, you should consult your accountant, attorney, or actuary. Neither M Financial Group, nor its Member Firms should replace those advisors.

Securities and Investment Advisory Services offered through M Holdings Securities, Inc., a Registered Broker/Dealer and Investment Advisor, Member FINRA/SIPC. Rose Street Advisors, LLC is independently owned and operated. File #5354095

Interested in more?

Let's Talk Proactive HR

Have you seen Billy Madison starring Adam Sandler?  Do you remember the premise? His dad built a massive business and wanted to hand it over to his son… while Billy was busy having a full argument between shampoo and conditioner.

It’s funny because it’s exaggerated. But it also lands because there’s a real question underneath it.

What happens when something significant gets handed to someone who isn’t ready for it?

There’s a statistic that gets quoted often in our industry. Roughly 70% of wealthy families lose their wealth by the second generation, and about 90% by the third.

Not because people didn’t work hard. Not because there wasn’t enough. But because something didn’t carry forward.

So the real question isn’t just how to pass wealth on.

It’s this:

How do you prepare them for it?
How do you make sure what you built is amplified—not quietly diluted—in the next generation?

And when you’ve spent decades getting here, that question matters.

A client said something to me recently that stuck.

“We’ve spent decades building this. I’m just not sure our kids understand what it represents.”

Not from a control standpoint. From a place of respect for what it took to build it. If you step back for a moment, what you’ve built didn’t happen by accident. It took discipline, trade-offs, tough decisions that weren’t always obvious in the moment and staying steady when things were uncertain.

You earned the position you’re in. And because of that, your kids have grown up with more stability, more options and fewer constraints.

That’s something to be proud of.

At the same time, it creates a natural gap. They didn’t have to go through what you did to get here.

So it’s worth asking:

• What are they picking up from that difference?
• How do they view money, effort, and responsibility?
• Do they see this as something to build on—or something that will always be there?

Not because anything is wrong. But because they’ve had a different starting point.

And that shapes how things are interpreted.

The Real Question

The wealth didn’t just appear. It followed a way of operating.

Consistency, discipline, integrity and a willingness to do hard things over time. The ability to stay steady when others didn’t. Those weren’t side traits. They were the reason it worked.

So it’s fair to ask:

If those don’t carry forward, why would we expect the outcome to?

And if they did carry forward, what might that make possible?

Start Here

Most people have never actually defined what drove their success. They lived it, but they haven’t put clear language around it.

A simple place to begin:

Look backward.

Think about decisions you’re proud of. Not financially—personally. What did those moments have in common?

Then separate results from behavior.


The outcome isn’t the lesson. The behavior that created it is.

And make it clear. Not just “work ethic,” but what that actually looked like in your life.

If it’s clear to you, it becomes easier for someone else to understand.

And once that clarity is there, the next step becomes more practical.

Then, Over Time

This isn’t about one conversation. It’s about what gets seen and picked up along the way.

Let them see how you think through decisions. Not just what you chose, but how you got there.

Give them responsibility in ways that fit where they are. Confidence tends to follow experience.

Connect money to purpose. What it’s for, what it supports, what it doesn’t replace. And bring them along gradually. Not all at once, but not all at the end either.

Over time, that builds something more valuable than information. It builds judgment. And this is where planning starts to look a little different.

At our firm, this is part of the conversation. Not just the numbers, not just the portfolio, but how everything connects to the people behind it. Because a well-built plan isn’t just about growing assets. It’s about preparing the people those assets are meant to serve.

You

Over the next few months, pay attention to the moments where your values naturally show up. When you make a decision, when something doesn’t go as planned or when you choose the harder path.

Instead of letting those moments pass, make them visible. A quick explanation or a story when it fits. Letting them see how you think in real time. If you did that consistently, what might they begin to understand? Not just about money. But about how to operate when it matters.


If more families approached it this way, wealth would carry something more with it. Not just assets, but understanding.

We’d likely see more examples of it being built upon, not just maintained—or lost. Not because the opportunities were different, but because the people stepping into them were ready.

That’s what ultimately determines whether something lasts.

And if this is something you’ve been thinking about, give us a call.  It’s worth continuing the conversation. Because getting this right doesn’t happen by accident—and it’s too important to leave to chance.

Jeremy Heavey

AIF ® , NSSA ® | FINANCIAL ADVISOR

Securities and Investment Advisory Services offered through M Holdings Securities, Inc., a Registered Broker/Dealer and Investment Advisor, Member FINRA/SIPC. Rose Street Advisors, LLC is independently owned and operated. File #5321675

Interested in more?

Let's Talk Proactive HR

Steady Oversight and a Disciplined Process

Recent geopolitical developments have understandably raised questions about how global conflicts may affect financial markets. Periods like these can create uncertainty and volatility, and part of our responsibility as your advisors is to watch developments closely while keeping portfolios aligned with long-term objectives.

While headlines can feel unsettling, history shows that markets have navigated wars and geopolitical conflicts many times before. Keeping that historical perspective and remaining committed to a disciplined investment process helps guide decision-making during uncertain periods.

Stock Markets

• In the short term, markets often experience heightened volatility. Uncertainty around trade, energy markets and global supply chains can lead to sharp price swings

• Over the longer term, equity markets have historically recovered and moved higher. Wars can stimulate certain industries such as defense, manufacturing and infrastructure. Governments often implement policies designed to support economic stability and recovery.

Historical perspective and recovery timelines:

• During World War II, U.S. stocks dropped sharply following the attack on Attack on Pearl Harbor in December 1941. The decline was relatively brief; by mid-1942 markets had stabilized, and by 1943 equities were trending higher. The S&P 500 then moved into a multi-year expansion that continued through the post-war economic boom.

• During the Gulf War, the S&P 500 declined roughly 15–17% between July and October 1990 as oil prices spiked and uncertainty increased. Once the U.S.-led coalition began military operations in January 1991, markets recovered quickly. Within about six months of the market low, equities had regained their losses and continued advancing through the early 1990s expansion.

• During the Iraq War, markets had already been under pressure due to the bursting of the tech bubble and broader economic uncertainty. The S&P 500 bottomed in March 2003, almost exactly when the invasion began, and rose more than 25% over the following 12 months. That recovery marked the beginning of a broader bull market that lasted until 2007.

Bond Markets

• Government bonds are often viewed as a “flight to safety” during periods of conflict. When investors seek stability, demand for bonds can increase and yields may decline.

• At the same time, large government spending during wartime can introduce inflation pressures, which may influence interest rates and bond market dynamics.

Our Investment Management Philosophy

Even during uncertain times, our investment decisions remain guided by a disciplined philosophy focused on long-term outcomes rather than short-term headlines. Portfolios are constructed around each client’s goals, risk tolerance, and time horizon, using the information gathered through our discovery process and risk assessment tools.

Risk and return are related and building wealth over time requires staying invested and allowing capital to work through market cycles. Our approach emphasizes time in the market rather than attempting to time short-term movements. Instead of chasing individual “hot” investments or trying to predict market turning points, we focus on disciplined portfolio construction, broad diversification, and strategic allocation.

While geopolitical conflicts can create uncertainty in the short term, history reminds us that markets have faced many similar periods. It is important to remain disciplined in portfolio management, diversification and continue to stay aligned with your long-term financial goals.

Jeremy Heavey

AIF ® , NSSA ® | FINANCIAL ADVISOR

Scott Higgins

AIF ® , CFP ®, CPFA ®, NSSA ® | FINANCIAL ADVISOR

Securities and Investment Advisory Services offered through M Holdings Securities, Inc., a Registered Broker/Dealer and Investment Advisor, Member FINRA/SIPC. Rose Street Advisors, LLC is independently owned and operated. File #5303566

Interested in more?

Let's Talk Proactive HR

2026 Is the Year: Give at Least $2,000 to Non-Profits!

Every donation helps fuel the vital work of non-profits in our communities—feeding families in need, supporting local schools, foundations, church, funding scholarships, shelters, and programs that create lasting change. Your generosity, big or small, makes a real difference in the lives of people who rely on these organizations every day.

For anyone who loves to give, the last few years have been… a little frustrating. Why? Because the standard deduction—the basic amount the IRS lets everyone deduct without itemizing—kept getting bigger. For many donors, that meant small and medium gifts didn’t help your taxes at all. You could give $5,000 to your favorite cause, and nothing changed on your return. Ouch.

Here’s the story: back in 2018, the standard deduction nearly doubled, and it’s been rising gradually ever since. That’s good news for simple taxes, but it made it harder for regular givers to “see” any tax benefit unless you were donating big—think tens of thousands. For everyday philanthropists, your generosity was, in a sense, invisible on your tax form.

But 2026 is different. This year, for the IRS is letting up to $1,000 (single filers) or 2,000 (married filing jointly) of cash count on top of your standard deduction—even if you don’t itemize. That means your giving can reduce your taxes and make a real difference for the causes you care about.

Think of it like this:

   • You make $1,000 (or $2,000 for married filing jointly) in donations to non-profits.

   • You still take the standard deduction ($16,100 for single filers and $32,300 for married filing jointly).

   • If you’re in the 22% federal tax bracket, your donation could save you $440 in taxes. 

       If you are in a higher tax bracket, the savings are even larger.

For anyone who’s felt that donating “just a few thousand” never mattered, this is your moment.

2026 is your year to give boldly. Whether it’s your local school, a scholarship fund, church or a charity with a mission close to your heart, your generosity will make a bigger impact than ever before—both for the world and for your wallet.

Make this the year your giving truly pays off.

Jeremy Heavey

AIF ® , NSSA ® | FINANCIAL ADVISOR

Securities and Investment Advisory Services offered through M Holdings Securities, Inc., a Registered Broker/Dealer and Investment Advisor, Member FINRA/SIPC. Rose Street Advisors, LLC is independently owned and operated. File #5057707

Interested in more?

Let's Talk Proactive HR

The HSA Strategy Retirees Wish They Started Sooner

For high-net-worth individuals, an HSA can be more than a place to pay today’s medical bills — it can act as a health-care retirement account, offering long-term tax savings and a dedicated pool for future medical costs.

The Triple-Tax Advantage

HSAs offer one of the strongest tax combinations available:

1. Pre-tax contributions from payroll deduction that lower taxable income

2. Tax-free investment growth

3. Tax-free withdrawals for qualified medical expenses — even years later

Grow It Like a Retirement Account

Investing most of the HSA — similar to an IRA or 401(k) — lets balances compound for decades.
Rose Street Advisors encourages keeping a money-market cash buffer inside the HSA, covering an unexpectedly expensive medical year while leaving the rest invested for growth.

Keep Receipts & Reimburse in Retirement

A powerful strategy is to pay out-of-pocket even using a credit card to get the miles/points/cash back.

Store every receipt in a digital vault, and reimburse yourself later in retirement.  This keeps more dollars invested and growing tax-free while maintaining flexibility for future withdrawals. 

Healthcare Costs Are Higher Than People Think

A healthy 65-year-old couple may need about $388,000 for healthcare costs in retirement under Medicare + Medigap Plan G + Part D (Milliman Retiree Health Cost Index, 2025).  This excludes long-term care, making proactive planning essential.

Best Practices

1. Max out annual contributions (use catch-ups if eligible) through payroll deduction.

2. Invest HSA funds for long-term growth.

3. (Optional) Keep a money-market buffer inside the HSA in the event you need to use the funds for a costly medical year.

4. Pay expenses out-of-pocket when possible and even use a credit card that earn points/miles/cash back (and pay it off each month).

5. Store receipts in a digital vault for future tax-free reimbursements.

6. When in retirement, reimburse yourself for the total of your receipts to maximize compounding.

7. Then, treat the HSA as a health-care retirement account paying for medical expenses with pre-tax dollars in retirement.

Used strategically as a part of your overall financial life plan, an HSA becomes a tax-efficient engine for future healthcare expenses — protecting and growing wealth while working and giving retirees flexibility and long-term control. 

Jeremy Heavey

AIF ® , NSSA ® | FINANCIAL ADVISOR

Securities and Investment Advisory Services offered through M Holdings Securities, Inc., a Registered Broker/Dealer and Investment Advisor, Member FINRA/SIPC. Rose Street Advisors, LLC is independently owned and operated. File #5052118

Interested in more?

Let's Talk Proactive HR
Next Page »
Rose Street Advisors

Your guide from hire to retire. Rose Street Advisors provides the strategy companies need to grow with confidence.

Firm
About UsOur TeamCommunity SupportTestimonials
Services
Employee BenefitsHR ConsultingLife InsuranceEmployer Retirement PlansWealth ManagementFiduciary Fitness
Contact

244 North Rose Street
Kalamazoo, MI 49007

5181 Plainfield Ave NE
Grand Rapids, MI 49525

269.552.3200
© 2026 Rose Street Advisors LLC. All rights reserved.
Securities and Investment Advisory Services Offered Through M Holdings Securities, Inc. A Registered Broker/Dealer and Investment Advisor, Member FINRA/SIPC. Rose Street Advisors is independently owned and operated. Please go to www.mfin.com/DisclosureStatement for further details regarding this relationship. Check the background of this Firm and/or investment professional on FINRA's BrokerCheck. For important information related to M Securities, refer to the M Securities' Client Relationship Summary (Form CRS) by navigating to mfin.com/m-securities. Registered Representatives are registered to conduct securities business and licensed to conduct insurance business in limited states. Response to, or contact with, residents of other states will only be made upon compliance with applicable licensing and registration requirements. The information in this website is for U.S. residents only and does not constitute an offer to sell, or a solicitation of an offer to purchase brokerage services to persons outside of the United States. This site is for information purposes and should not be construed as legal or tax advice and is not intended to replace the advice of a qualified attorney, financial or tax advisor or plan provider. CA Insurance License. File #5757992.1

We value your privacy

We use cookies to keep this site reliable, understand how it’s used, and — with your permission — to personalize content. You can accept all, reject non-essential, or choose which categories to allow.

Privacy Policy

Cookie Preferences